

The state of Ohio has one of the best 457(b) Deferred Compensation plans in the country. In addition to the multiple NAGDCA awards it has received, the plan earns a Green rating (the highest) from 403bwise.org for offering low-cost index funds and low administrative fees, including no fees for accounts with less than $5,000.
So why did the largest association in Ohio representing school business officials start a more costly competitor?
The state of Ohio created the deferred compensation plan (a section 457(b) retirement plan) in 1976. It is public law and acknowledged that “The Board, staff, and consultants are all fiduciaries acting solely in the best interests of Ohio DC participants.” The plan had nearly $22 billion in assets as of the end of December 2024 and annual contributions that exceeded $650 million.
The Ohio 457(b) plan is the best example of how to integrate a state plan with public school districts properly (it’s very simple for most Ohio educators to enroll online).
By all accounts, it’s one of the best-run state 457(b) plans in the nation.
So why did the Ohio Association of School Business Officials (OASBO) decide to create its own program and push it on school districts?
We guess it pleased their association sponsors, who were upset they couldn’t get a piece of the 457(b) pie.
Did the OASBO create a better program? We decided to do the research and find out.
Sneak peek, it’s not pretty.
First, I cannot find any mention of fiduciary duty regarding these plans on any of the OASBO websites or the vendors (Equitable and Voya) that recordkeep the program. There is no mention of fiduciary duty on the part of the compliance administrator either. Who are the fiduciaries running these plans?
It appears no one is willing to be named as a fiduciary (again, I could be wrong; there may be a named fiduciary, but I just can’t find it publicly disclosed).
The lack of fiduciary responsibility becomes apparent upon closer inspection.
One OASBO vendor (Voya) charges 36 times what the Ohio 457(b) plan charges for a similar investment (US large-company stocks), while the other vendor (Equitable) charges 67 times as much. While the indexes used differ slightly, the returns over long periods will be virtually the same before fees.
What brilliant mind at OASBO thought this was acceptable?
Here is a comparison of the fees among the two OASBO vendors and the Ohio 457(b):
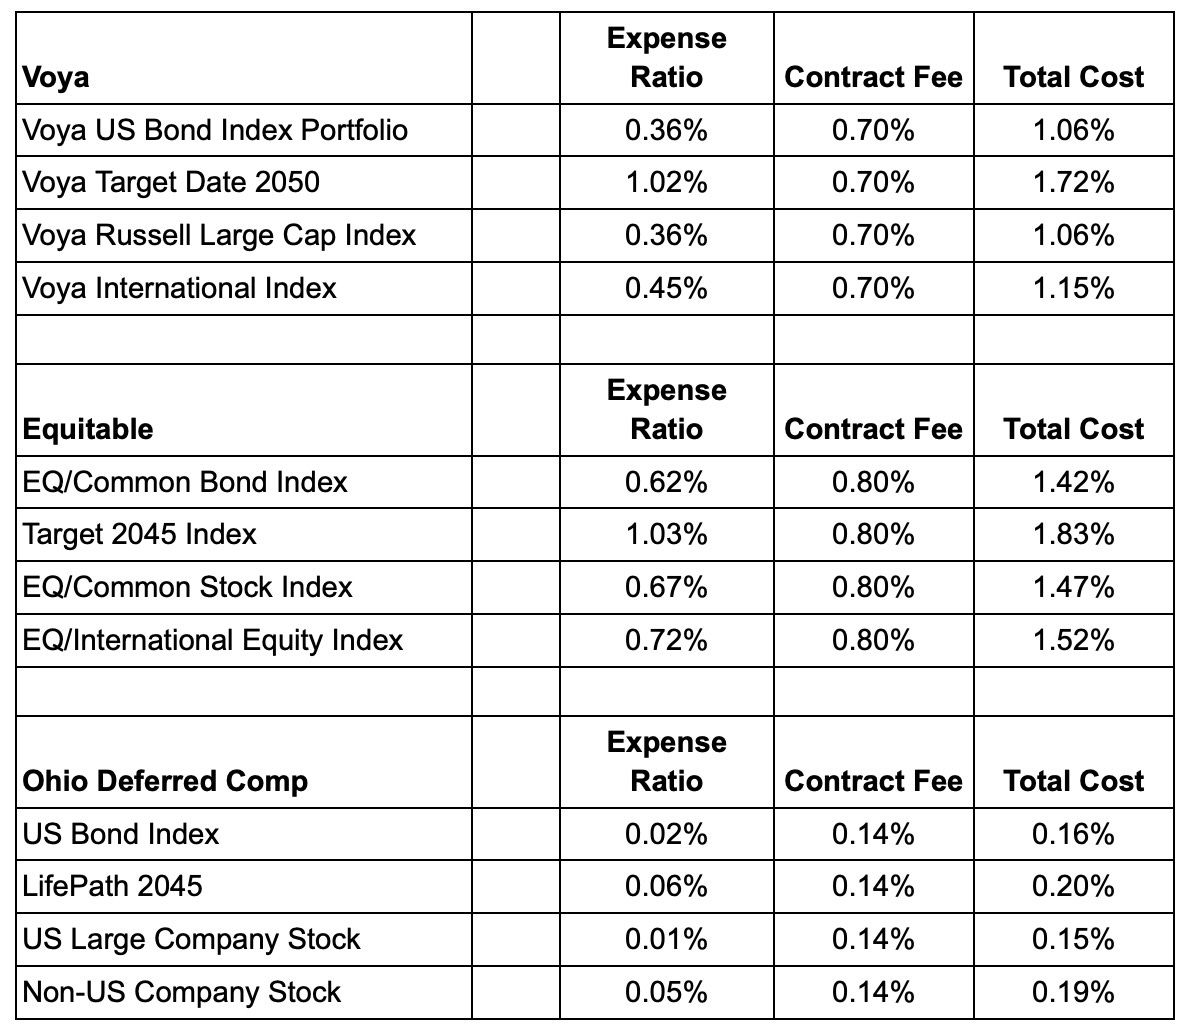
Finding the fees for the Ohio Deferred Compensation plan was simple. It took me less than two minutes. In fact, the fees disclosed above don’t adequately cover the actual fees for the Ohio 457(b); they’re even better.
The Ohio 457(b) does not charge a fee on the first $5,000 in account balance.
The Ohio 457(b) limits its fee to $55 per quarter or $220 per year, meaning the 0.14% administrative fee is lower for higher account balances.
The Ohio 457(b) doesn’t allow its investment lineup to use investment options that are packed with excess fees that pay revenue share back to the recordkeeper or plan sponsor.
The Ohio 457(b) doesn’t trap its employees in the plan with long surrender periods and high surrender charges, unlike the OASBO plan (Voya’s surrender charge starts at 5%, Equitable’s at 6%, and doesn’t go away for ten years).
The Ohio 457(b) doesn’t charge a $30 annual fee on account balances under $25,000, unlike OASBO’s Equitable product.
The Ohio 457(b) doesn’t use expensive, proprietary investment options as OASBO’s Equitable and Voya products do.
I decided to run an analysis of the fees a participant would pay to own the Target Date Option with Ohio 457(b) versus the OASBO vendors. The results were revealing:
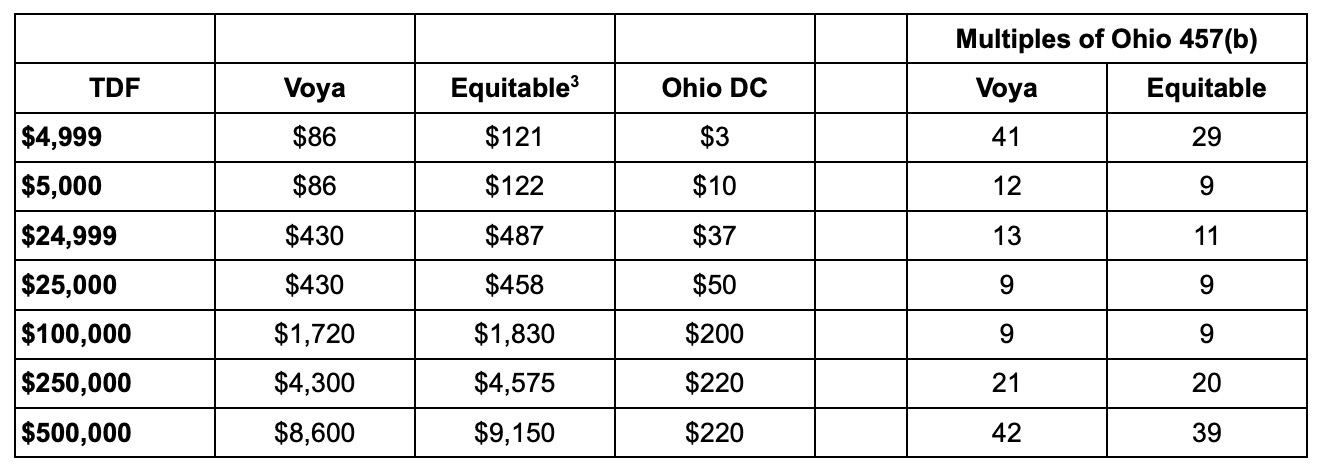
Even at account balances as low as $5,000, the OASBO program charges up to 12 times the Ohio 457(b) rate.
Did I mention that the Ohio 457(b) doesn’t charge a penny in administrative fees on the first $5,000?
At best, the OASBO program charges participants 9 times as much as the Ohio 457(b) plan.
At worst, the OASBO program may charge participants 42 times what the Ohio 457(b) plan charges.
The OASBO 457(b) program is not serious.
The OASBO 457(b) program does not appear to have been created to assist educators; it seems to exist to loot educators.
The question has to be asked: why did OASBO decide to put this program in place when they knew educators already had an immensely better program available to them?
Is it possible that the OASBO sponsors and the money they give to OASBO are responsible for this awful program?
We have spoken to hundreds of school business officials over the years, and we know how hard they work and how dedicated they are to their employees. We know that if they were made aware of what was being done in their name, they would not be happy. After all, school business officials participate in these programs also; they deserve better.
OASBO should shut down this abomination of a program, apologize to the people in it, and tell them to use the superior Ohio 457(b) plan run by fiduciaries.
403bwise.org does not receive a penny from the Ohio 457(b) and was not asked to do this analysis, so we decided to review this program after the NTSA posted an article that mentioned the OASBO program and also provided misleading information about 457(b) plans.